Iran's Islamic Revolutionary Guard Corps navy struck a supertanker in the Strait of Hormuz. According to Tehran, the vessel had turned off its automatic identification system and was following an unauthorized route. This was the third ship attacked in these waters in two days. Escalation in the Middle East and continued Houthi strikes are keeping Brent crude above $100/bbl. The geopolitical risk premium outweighs signals of potential supply increases, including a resumption of Gulf of Mexico output after the hurricane. It is the combination of several risks that helps Brent hold above $100 even after reports of possible supply additions.
While energy prices and bond yields are rising, the threat of further Fed rate hikes this year remains. As a result, major Wall Street indices traded mixed on Monday:
Strong expectations for third-quarter corporate profits are offsetting tight credit conditions caused by high Treasury yields. Expensive fuel is meanwhile reinforcing the Fed's hawkish stance. That produced sector rotation in the equity market:
Safe-haven relationships rotated as well. Non-yielding silver and gold clearly lost ground to the dollar, which rose to an 18-month high. Precious metals resumed their slide:
One driver of the greenback rally was market caution ahead of US consumer and producer inflation releases (CPI, PPI), as well as retail sales data. CME FedWatch puts the odds of an October Fed rate hike below 20%, while the chance of a December move is about 85%. Wall Street Journal experts expect US Treasury yields to remain high through next year.
What keeps Treasuries attractive — and thus underpins dollar demand — is the calendar risk. The decisive near-term Fed input will be the September US inflation report: softer readings would give the Fed room to delay a rate increase until December, reducing market volatility. Investors are also watching the IMF and World Bank annual meetings.
October 13, 02:01 / United Kingdom / ** / BRC Retail Sales (September) / prev.: 1.0% / actual: 0.5% / cons.: 0.7% / GBP/USD — up
Retail sales growth in the UK for August slowed sharply, showing the weakest print since autumn 2024. Consumer activity was hit by:
Analysts expect a modest pickup in retail sales in September, which could provide some support for the British pound.
October 13, 02:50 / Japan / ** / Producer Price Index (PPI) (September) / prev.: 7.7% / actual: 7.6% / cons.: 7.6% / USD/JPY — volatile
Japan's producer prices in August remained close to multi-year highs, registering one of the strongest growth rates since early 2023. Pro-inflationary pressure was broad-based, led by:
Markets are pricing in sustained annual PPI inflation in September. Persistently high input costs for businesses raise the odds of tighter policy from the Bank of Japan, which could support the yen.
October 13, 03:30 / Australia / ** / NAB Business Confidence (September) / prev.: -6 / actual: -8 / cons.: -9 / AUD/USD — down
Australia's business confidence index for August fell to its lowest level since May. The business environment showed a six-year low in activity driven by weaker sales, margin compression, and job cuts. Ongoing cost pressures and a drop in the pipeline of future orders are forcing firms to be cautious on investment and hiring. Economists forecast further deterioration in business sentiment for September. Cooling in manufacturing and trade activity will likely put pressure on the Australian dollar.
October 13, 09:00 / Germany / *** / Consumer Price Index (CPI) (prelim., September) / prev.: 2.8% / actual: 2.9% / cons.: 3.3% / EUR/USD — up
Germany's annual consumer inflation accelerated sharply in the preliminary September read, reaching its highest level since late 2023. Key drivers of the price surge included:
Analysts had expected further upward pressure on annual inflation. A firmer inflation backdrop increases the likelihood of a continued hawkish ECB stance, which could support the euro.
October 13, 15:15 / US / ** / ADP Average Weekly Job Gains / prev.: 20.0k / actual: 23.75k / cons.: — / USDX (six-currency dollar index) — volatile
Private-sector average weekly job gains for the third week of September came in at 23.75k, marking the fastest hiring pace in three months. The trend points to a resilient underlying labor market. Accelerating payroll activity will provide support to the US dollar.
October 13, 17:00 / US / ** / Existing Home Sales (September) / prev.: 4.06m / actual: 3.98m / cons.: 3.96m / USDX — down
US existing home sales fell by 2.0% month-on-month in August, reflecting higher mortgage rates driven by rising energy costs and stronger bond yields. Factors shaping the sector's results included:
Markets are positioning for further softness in existing home sales. Cooling housing demand will likely weigh on the greenback.
October 14, 04:30 / China / *** / Consumer Price Index (CPI) (September) / prev.: 0.5% / actual: 0.8% / cons.: 1.0% / Brent — up, USD/CNY — down
China's consumer inflation accelerated in September, rebounding from a multi-month low. Key contributors to the rise included:
Analysts expect further acceleration in consumer prices. A stronger inflation impulse and rising domestic demand in China would support commodity markets and push the yuan stronger.
October 14, 04:30 / China / ** / Producer Price Index (PPI) (September) / prev.: 3.5% / actual: 3.8% / cons.: 4.5% / Brent — up, USD/CNY — down
China's producer prices rose in September, beating consensus. Drivers of producer price inflation included:
Markets are pricing in a material pickup in industrial inflation for September. Strength in the manufacturing sector and higher commodity prices could support Brent and press USD/CNY down.
October 14, 05:00 / China / *** / Trade Balance (September) / prev.: $112.5bn / actual: $119.1bn / cons.: $114.5bn / Brent — down, USD/CNY — up
China's trade surplus widened notably in September, powered by strong exporters. External trade highlights included:
Analysts expect the export surplus to remain elevated in the near term.
October 14, 09:00 / Germany / ** / Wholesale Prices (September) / prev.: 5.3% / actual: 6.8% / cons.: 7.0% / EUR/USD — up
Germany's wholesale prices accelerated sharply in September, hitting the highest rate since early 2023. Strong price pressure at the wholesale level was driven by:
Analysts expect further acceleration in wholesale inflation for September. Rising input costs at early production stages increase the likelihood of a hawkish European Central Bank, which could support the euro.
October 14, 15:30 / Canada / ** / Building Permits (August) / prev.: 18.3% / actual: -17.3% / cons.: 3.1% / USD/CAD — down
Building permits in Canada plunged in August to their lowest level since summer 2023. The deterioration reflected:
Economists expect a solid recovery in permit issuance in September. A restart in developer activity could support the Canadian dollar.
October 14, 15:30 / US / *** / Consumer Price Index (CPI) (September) / prev.: 3.4% / actual: 3.4% / cons.: 3.7% / USDX (six-currency dollar index) — up
US annual consumer inflation for September held steady at the prior reading, matching market expectations. Price dynamics were shaped by:
Analysts expect further upward pressure on CPI. Stronger inflation could support the dollar.
October 14, 23:30 / US / ** / Crude Oil Inventories (API, week to Oct. 2) / prev.: +1.019m bbl / actual: -2.09m bbl / cons.: — / Brent — up
US commercial crude inventories fell in the week to October 2, reversing the prior week's build. Market details included:
A sizeable draw in commercial crude inventories could support Brent crude prices.
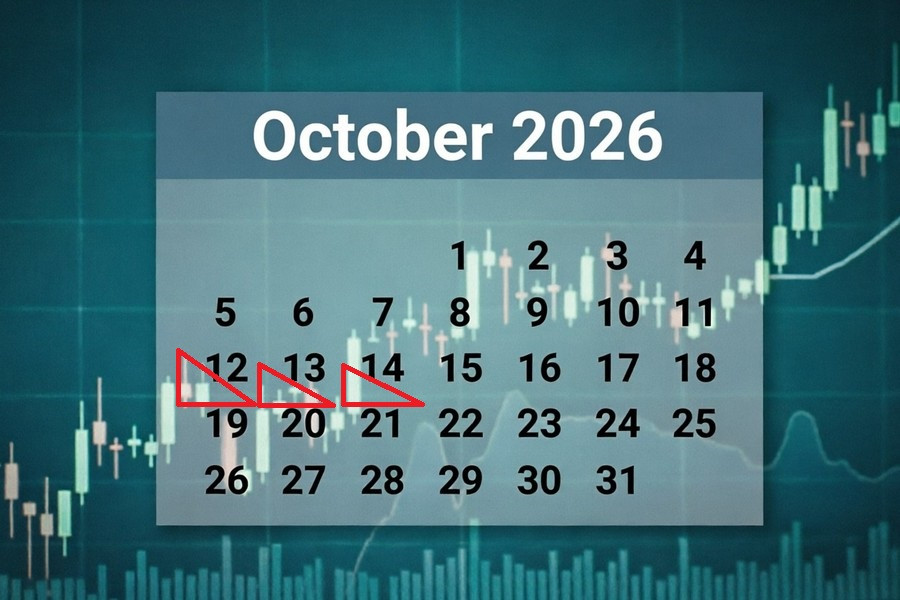
Oct. 12–18 / IMF and World Bank Annual Meetings (Bangkok, Thailand)
Oct. 12, 12:30 / United Kingdom / Speech by BoE Deputy Governor Sarah Breeden / GBP/USD
Oct. 12, 15:50 / United Kingdom / Speech by Catherine Mann, BoE Monetary Policy Committee / GBP/USD
Oct. 13, 09:05 / Canada / Speech by Bank of Canada Governor Tiff Macklem / USD/CAD
Oct. 13, 19:10 / US / Speech by Cleveland Fed President Beth Hammack / USDX
Oct. 13, 03:30 / Australia / Release of RBA minutes (Sept. 29 meeting) / AUD/USD
Oct. 13, 06:00 / UK / Speech by Megan Greene, BoE Monetary Policy Committee / GBP/USD
Oct. 13, 10:15 / Eurozone / Speech by Frank Elderson, ECB Supervisory Board / EUR/USD
Oct. 13, 10:45 / US / Speech by Fed Governor Christopher Waller / USDX
Oct. 13, 19:00 / UK / Speech by Swati Dhingra, BoE Monetary Policy Committee / GBP/USD
Oct. 13, 20:00 / US / Speech by Richmond Fed President Thomas Barkin / USDX
Oct. 13, 20:30 / Eurozone / Speech by Philip Lane, ECB Governing Council / EUR/USD
Oct. 13, 23:00 / US / Speech by Boston Fed President Susan Collins / USDX
Oct. 14, 05:10 & 11:30 / Eurozone / Speeches by ECB President Christine Lagarde / EUR/USD
Oct. 14, 06:30 / UK / Speech by BoE Deputy Governor Sarah Breeden / GBP/USD
Oct. 14, 08:30 / UK / Speech by Bank of England Governor Andrew Bailey / GBP/USD
Oct. 14, 09:00 / UK / Speech by Hugh Pyle, BoE Monetary Policy Committee / GBP/USD
Oct. 14, 09:05 / Canada / Speech by Bank of Canada Governor Tiff Macklem / USD/CAD
Oct. 14, 11:00 / Eurozone / Speech by Frank Elderson, ECB Supervisory Board / EUR/USD
Oct. 14, 11:15 / Eurozone / Speech by Claudia Buch, ECB Single Supervisory Board / EUR/USD
Oct. 14, 12:40 / US / Speech by Fed Governor Michelle Bowman / USDX
Oct. 14, 19:15 / Eurozone / Speech by ECB Executive Board Member Isabel Schnabel / EUR/USD
Oct. 14, 20:30 / US / Speech by Richmond Fed President Thomas Barkin / USDX
Oct. 14, 21:00 / US / Release of the Fed's Beige Book (regional economic summary) / USDX
Numerous central bank officials are scheduled to speak during the IMF/World Bank meetings. Their comments typically trigger FX volatility because they can shed light on future interest rate paths.
The economic calendar is available via the link. All indicators are shown year-over-year (y/y) unless otherwise noted; monthly figures are marked (m/m). Trade balance, export, and import values are listed in the local currency. Asterisk (*) denotes the report's importance for instruments available on the InstaForex platform (in ascending order). Publication times are stated in Moscow time (GMT+3). Open a trading account here. See also InstaForex market video updates and download the MobileTrader app to keep instruments at hand.
HIZLI BAĞLANTILAR
show error
Unable to load the requested language file: language/turkish/cookies_lang.php
date: 2026-10-13 04:07:26 IP: 172.18.0.1


 Bize Ulaşın