By the end of yesterday, the euro had recovered all the losses seen at the start of the week. The pound showed a similar picture, advancing steadily toward larger resistance zones at 1.3282 and 1.3307, where new big sellers may appear. On Monday EUR/USD hit monthly lows on a thin market, and GBP/USD returned to the lower boundary of its sideways channel; today's picture looks almost mirror-opposite. The reason lies in the data and, above all, in one speech.
German figures fully matched economists' forecasts. In September the consumer-price index rose 0.6% month-on-month and 3.3% year-on-year, unrevised from preliminary data (annual inflation was 2.9% in August). This produced no market pressure. The NFIB small-business optimism index for September came in at 97.9 versus a 98 forecast and 98.7 previously — again essentially in line with expectations. ADP weekly employment data for October were also roughly as expected, +24.8k versus +25k three weeks earlier. The housing sector looked best: existing-home sales in September rose to 3.99 million, nearly 4 million, versus a 3.95 million forecast; month-on-month sales rose 1.5% after a 3.2% decline previously. That's a solid print and produced a small, short-lived dollar-buying reaction.
The key was New York Fed president John Williams' remarks, which significantly weakened the US currency. He said he sees only one rate hike as appropriate this year and currently sees no grounds for further tightening. For those expecting a firmer Federal Reserve stance, this was a cold shower. Recall that on September 2 Williams said there was no need to rush after the September increase to 3.75–4.00% and one could await new data — and on that basis Beth Hammack's hawkish comments lose weight. Still, one should not rely solely on a single official's words; there remain hawks who consider further tightening necessary. The market has already priced Williams' statement, and there is no need to over-emphasize it going forward.
Now to today's economic calendar — it is fairly eventful. In the first half of the day, Bank of England governor Andrew Bailey will speak. If his tone is hawkish, the pound will receive an upward impulse versus the dollar. Recall the Bank Rate is 3.75%, and three MPC members voted in July for immediate tightening, so any shift in the governor's emphasis will be read as a signal. European Central Bank President Christine Lagarde will also speak. The ECB has adopted a fairly restrictive stance — after the September hike, the deposit rate stands at 2.50% — and Lagarde has said overall inflation is likely to remain notably above target until the first half of 2027. If she maintains that tone, the euro could continue its recovery in the first half of the day, especially since markets still price a pause on October 29 and one final hike in December to 2.75%.
The main focus today, however, will be US inflation. Headline consumer prices for September are expected to rise 0.6% after 0.4% in August, and to accelerate to 3.7% year-on-year from 3.4%. By comparison, August's figure was driven largely by gasoline and energy, which were up 16.3% year-on-year, and the ISM services prices index for September reached 74. The readings are far from the 2% target. The core index looks better: month-on-month growth is expected at only 0.2% after 0.3% in August, and 2.5% year-on-year after 2.4%. That is a small annual increase and not far from the target. If the prints significantly exceed forecasts, dollar demand will return. If they match or come in softer, the euro and the pound could recover well. Fed speakers scheduled include Michelle Bowman and Thomas Barkin. Bowman was listed among potential dissenters on the September hike, and Barkin has previously warned that the bill for the current policy is still to come. We will see what stance they take, since the Fed shows clear divisions: Hammack spoke for further hikes while Williams argued they are unnecessary. Market expectations remain unchanged for now — a pause on October 28 and a hike on December 9 priced at about 80% probability.
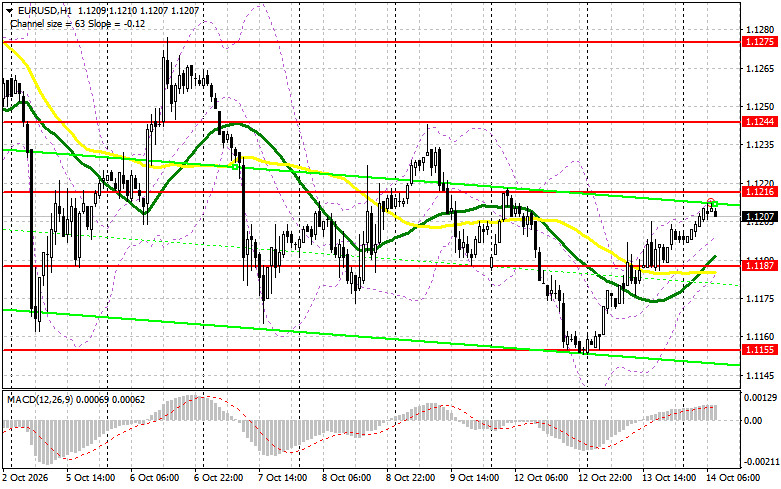
EUR/USD — if the correction continues, the 1.1216 level is interesting for selling on a false breakout. A solid close above this range would give a strong bullish impulse toward 1.1244; there I would also consider short positions if the close fails, or look to sell a retracement from 1.1275 targeting a 25-30 pip move. Buying on dips is possible from 1.1187 (the moving-average area) if it fails to close below, which could produce a bullish impulse. If no buyers show at 1.1187, a break of that range will likely push the euro to 1.1155, keeping us within the sideways channel. A break of 1.1155 would open the way to 1.1126, where bounce buys targeting 25–30 pips are possible. I consider long positions from 1.1155 and 1.1187 only if those are false breakouts.
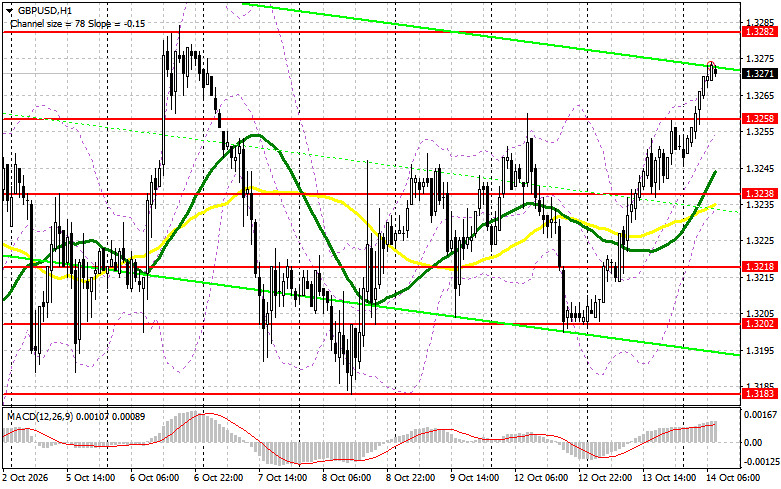
GBP/USD — as noted, a fairly large recovery is underway. I expect the first more aggressive sellers at 1.3282. On a false breakout, a drop toward 1.3258 is likely, and if buyers exist, they will try to hold that level during the European session after such a strong Asian rise. Therefore, a failed close above 1.3282 would be a reason to add longs, especially since there is no material UK fundamental data today beyond BoE speeches. A confirmed break and close above 1.3282 — as we saw yesterday around 1.3238 — would be a good entry for longs. The same scenario at 1.3282 would offer a chance to rise to 1.3307, where short positions are only for a failed breakout, or shorts on a retracement from 1.3341 targeting 25–30 pips. If buyers fail to show at 1.3258, I expect a larger correction toward 1.3238 (the moving-average area), where failed downside breakouts present buying opportunities. I would look to buy rebounds from 1.3218, targeting about 20–25 pips.
I personally lean toward the view that until US inflation is released, the market will stay in recovery mode, and the key factor will be the difference between expectations for the core index and the headline number. I would venture that with a soft print, the euro and pound will reach the indicated resistances, although they may not hold above them immediately. I do not rule out that hawkish comments from Bowman or Bailey in the morning could alter this scenario before the data are released.
QUICK LINKS


 Contact Us