It appears Tehran has thoroughly revised the fundamentals of its military strategy. The Islamic Revolutionary Guard Corps (IRGC) has officially announced that the Islamic Republic's military doctrine will henceforth
It appears Tehran has thoroughly revised the fundamentals of its military strategy. The Islamic Revolutionary Guard Corps (IRGC) has officially announced that the Islamic Republic's military doctrine will henceforth be explicitly "offensive and asymmetric." IRGC spokesman Brigadier General Hossein Mohebbi told SNN in an interview that the prior concept—limited to defensive actions and retaliatory strikes only in the event of direct aggression—is a thing of the past. The Iranian command now openly threatens full-scale incursions into any country that attempts an attack.
The aim of the new doctrine is to inflict such a pre-emptive blow on an adversary that it fully appreciates Tehran's power and resolve. This hard rhetoric is matched by operations in the Persian Gulf maritime theater:
In Washington, by contrast, officials show a marked reluctance to pursue diplomatic compromise. President Donald Trump told the White House pool he categorically denies any talks with Tehran: "No, I think we're not negotiating. We are going to have something one way or the other that'll happen fairly soon. Most people seem to think it's after the election, and we're going to see what happens." He did not disclose details of any planned actions and described Iran's financial and military situation as critical.
Trump assesses that Iran simply "has no money" and that the Iranian army, navy, and air forces have been largely degraded by prior US operations. He called actions against Iran among the most outstanding decisions of his administration, arguing that only forceful military intervention prevented Iran from acquiring a nuclear arsenal. There is little doubt Washington will avoid escalation until after the vote, shielding the administration from electoral shocks.
The same dynamics are playing out in France, where protests against the rising cost of living have erupted. President Emmanuel Macron publicly acknowledged that the threat of a Strait of Hormuz cut-off was catastrophically underestimated by the international community. Traders, however, must distinguish strictly between oil, diesel, and gas: each market obeys its own dynamics, with its own supply-and-demand balance and specific culprits. Paradoxically, there is no global shortage of liquefied natural gas (LNG).
According to IEA calculations, global LNG deliveries in 2026 will be broadly unchanged from 2025. Lost Qatari and Emirati exports due to Gulf tensions were almost fully offset by new terminal capacity in the US, Australia, and several African states. Physical gas has not disappeared from world markets, yet spot prices have surged to record levels. The reason lies in buyer behavior — primarily European and Chinese purchases:
1. Failure of Europe's procurement strategy. European gas management mistakes began to show last autumn. EU traders deliberately underfilled underground gas storage (UGS) facilities, deeming current prices too high and hoping for seasonal declines. After the Hormuz blockade, prices did not fall but surged. European operators were forced into panic buying of LNG cargoes competing with Asian importers, which further pushed prices up. As a result, by October 1 average UGS fill levels in Europe were only about 72%—historically a disastrous level ahead of the heating season. Facing winter cold peaks with such stocks becomes an extreme survival test for the continent's energy system.
2. China's coal crisis. A second powerful price driver came from Beijing. A spring accident at a coal mining site in Shanxi province prompted draconian safety tightening across the country. Miners moved to strict regimes, triggering a sharp fall in coal output amid steadily rising electricity demand. The shortage of solid fuels forced Chinese authorities to fire up gas-fired generation and to sweep the global LNG market, depriving Europe of opportunities to buy available cargoes at reasonable prices.
Tensions in the Middle East and rising energy prices keep inflationary pressure high, yet the US bond market has found a pause. Investors actively buy discounted US Treasuries as a classic safe haven amid a broad tech sell-off and capital flight from over-heated AI-linked stocks. Fresh US macro releases showed a slowdown in homebuilder activity and residential market transactions collapsing to historic lows.
Ahead lies a series of meetings of major global central banks. Market consensus now nearly rules out policy changes next week: the Federal Reserve, the European Central Bank, and the Bank of Japan are all very likely to leave key rates unchanged. However, the geopolitical premium embedded in commodity contracts fans inflationary expectations, and its rise will prevent central banks from loosening policy prematurely.
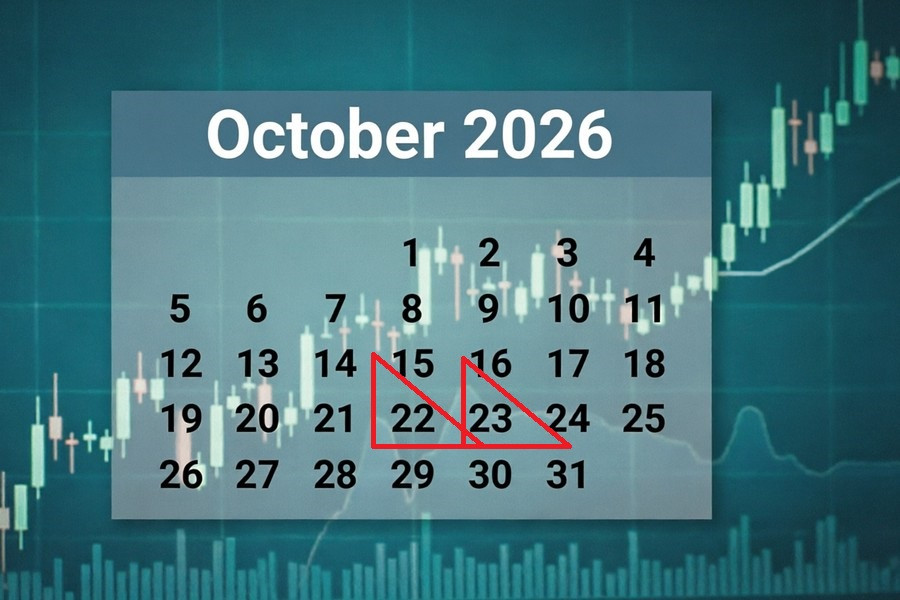
October 22, 09:00 / Eurozone / **/ New car registrations in September / prev.: 3.0% / actual: 4.5% / forecast: 10.1% / EUR/USD — up
The EU auto market posted its seventh consecutive month of growth in August, rising 4.5% on the back of a solid inflow of buyers into the electric vehicle segment. Fully electric vehicles (BEVs) accounted for 21.7% of total sales, with France, Germany, and Denmark the key growth drivers. Among the bloc's largest economies, Spain showed double-digit growth in registrations (+11.8%), while France, Italy, and Germany recorded more modest but steady increases. Analysts expect a marked acceleration in new car registrations in September. A strong pick-up in both consumer demand and auto production would support the euro.
October 22, 13:00 / United Kingdom / **/ CBI business optimism index Q4 (leading) / prev.: -65 / actual: -36 / forecast: -38 / GBP/USD — down
The quarterly business sentiment gauge from the Confederation of British Industry rebounded strongly in Q3, rising to -36 after a deep plunge in Q2. Despite the marked reduction in pessimism among manufacturers, the indicator remains far below its long-run norm, reflecting corporate caution amid high rates and geopolitical instability. Markets expect a moderate deterioration in business sentiment in Q4. Any renewed weakening of business confidence would weigh on the pound.
October 22, 13:00 / United Kingdom /**/ CBI manufacturing orders balance for October (leading) / prev.: -25 / actual: -9 / forecast: -20 / GBP/USD — down
September's CBI survey recorded the manufacturing orders balance at its best level since summer 2023. The industrial picture was shaped by:
Consensus for the October release assumes a noticeable pullback and deterioration in the manufacturing orders balance. A decline in order book indicators would put pressure on the pound.
October 22, 15:30 / Canada / **/ New home price for September (m/m) / prev.: -0.1% / actual: -0.1% / forecast: 0.4% / USD/CAD — down
August prices on Canada's primary housing market fell a token 0.1% month-on-month, repeating the trajectory of the prior two months. Near-zero dynamics in unit prices, with land values stabilizing, point to a gradual establishment of a price floor in homebuilding after an extended cooling driven by costly credit. Experts expect a clear return to growth in the primary housing market in September. A recovery in construction activity would support the Canadian dollar.
October 22, 15:30 / Canada / **/ Industrial producer price index (IPPI) for September / prev.: 12.3% / actual: 13.5% / forecast: 14.1% / USD/CAD — down
Output factory prices in Canada accelerated in August, rising more than one percentage point. Higher output costs have synchronized with a global upswing in commodity markets, forcing producers to pass elevated material costs into final goods prices. The September report anticipates further growth in industrial inflationary pressure. Stronger wholesale inflation increases the likelihood that the central bank will keep policy tight, which supports the Canadian dollar.
October 22, 15:30 / Canada / **/Raw materials price index (RMPI) for September / prev.: 18.2% / actual: 22.8% / forecast: 24.0% / USD/CAD—down
Annual growth in Canada's raw materials prices for August showed a powerful rally, reaching 22.8%—far above long-run averages for the past four decades. The sharp price surge was driven by global supply disruptions in energy and broad increases in key raw inputs for manufacturing. Analysts expect the raw materials rally to continue. High commodity export prices will provide substantial support to the Canadian dollar.
October 22, 15:30 / USA / **/Initial jobless claims / prev.: 198k / actual: 199k / forecast: 200k / USDX (six-currency USD index) — down
The weekly US Labor Department data show continued near-record stability: initial claims remain below the 200k threshold, and continuing claims fell to 1.71m, holding near three-year lows. Despite a local increase in claims from public sector workers, the overall labor picture supports a full employment scenario in the US economy. The next release is expected to show a modest rise in initial claims. Early signs of weakening hiring would put pressure on the US dollar.
October 22, 17:00 / Eurozone / ***/Consumer confidence for October (leading) / prev.: -15.5 / actual: -16.5 / forecast: -17.0 / EUR/USD — down
The eurozone's leading consumer confidence indicator fell to -16.5 in September, interrupting a four-month recovery. Household stress reflects a broad set of factors:
Analysts expect consumer pessimism to deepen in October. A weakening of domestic demand will weigh on the euro.
October 22, 18:00 / USA / **/ Kansas City Fed manufacturing index for October (leading) / prev.: 17 / actual: 20 / forecast: 18 / USDX — down
Manufacturing activity in the Federal Reserve Bank of Kansas City district reached its highest level since spring 2022 in September. The upswing covered both durable and nondurable goods, with the strongest impulse from furniture, rubber, and plastic makers. Key leading indicators confirm business revival: new order balances jumped to multi-month highs and shipments expanded notably, although rising input costs and cautious six-month managerial expectations continue to constrain hiring plans. The October report is expected to show a moderate cooling of regional manufacturing. Slowing activity would put pressure on the US dollar.
October 23, 01:00 / Australia /**/ S&P Global manufacturing PMI preliminary for October / prev.: 52.0 / actual: 49.6 / forecast: 49.4 / AUD/USD — down
Australia's manufacturing PMI plunged into contraction in September, marking the deepest deterioration in conditions in 21 months. The primary trigger was a synchronous fall in domestic and export demand: new orders ended a three-month upswing as competition and high input prices forced factories to cut output at the fastest pace since late 2024. Logistics delays from the Middle East crisis and adverse weather in Asia exacerbated the situation, leading to the first employment decline in the sector in five months. The preliminary October release is expected to show a further deepening of the industrial downturn. A worsening manufacturing picture will weigh on the Australian dollar.
October 23, 01:00 / Australia /**/ S&P Global services PMI preliminary for October / prev.: 53.2 / actual: 51.9 / forecast: 51.1 / AUD/USD — down
Australia's services sector remained in modest expansion in September, but growth slowed to a three-month low amid weak new business inflows. Despite a muted recovery in foreign orders, service firms began trimming staff to curb rapidly rising costs driven by more expensive fuel and labor. Higher production costs are being passed through into final prices, and with falling corporate confidence this raises questions about the sustainability of consumer demand. The October consensus points to further slowing in service activity. A cooling in services growth would weigh on the Australian dollar.
October 23, 02:01 / United Kingdom / **/ GfK consumer confidence for October (leading) / prev.: -14 / actual: -13 / forecast: -15 / GBP/USD — down
September's GfK survey showed an unexpected improvement in UK consumer sentiment to its best level in more than two years. Households became noticeably more upbeat about their personal finances and the national economic outlook, reflected in concurrent gains across related confidence metrics. Nevertheless, the indicator remains deeply negative, and a renewed bout of energy price inflation poses a serious risk of eroding consumer optimism ahead of winter. Analysts expect the measure to fall back in October. A return to weaker consumer confidence would weigh on the pound.
October 23, 02:30 / Japan / ***/CPI for September / prev.: 1.9% / actual: 1.9% / forecast: 2.3% / USD/JPY — down
Japan's annual consumer inflation for August stayed at the year's peak amid sustained price rises in household goods, food, and transport services. A rise in gas prices was offset by government energy subsidies for electricity, and core inflation excluding fresh food eased slightly for the first time in four months, remaining below the 2% policy benchmark. The September release is expected to show a material acceleration in consumer prices. A stronger inflation backdrop would raise the likelihood of further Bank of Japan tightening and support the yen.
October 23, 03:30 / Japan / **/S&P Global manufacturing PMI preliminary for October / prev.: 54.9 / actual: 54.1 / forecast: 59.5 / USD/JPY — down
Japan's manufacturing PMI held at 54.1 in September, indicating the slowest expansion since spring. Slower output and domestic sales came with lengthening supplier lead times, forcing firms to increase raw material inventories for the first time in over two years. Export demand and hiring remained resilient near multi-year highs, while inflationary pressure on input costs eased to a six-month low. The preliminary October reading anticipates a strong uptick in industrial activity. A meaningful revival in manufacturing would strengthen the yen.
October 23, 01:00 / Australia / **/ S&P Global services PMI preliminary for October / prev.: 53.2 / actual: 51.9 / forecast: 50.5 / AUD/USD — down
Australia's services sector showed its weakest expansion in three months in September. Slower inflows of new domestic business prompted firms to cut staff for the first time since May to rein in rapidly rising operating costs driven by higher fuel and labor prices. The need to pass higher input costs into final charges amid falling corporate confidence raises risks to demand sustainability. The October consensus expects activity to cool further toward the brink of stagnation. A slowdown in services growth will weigh on the Australian dollar.
October 23, 09:00 / United Kingdom / ***/ Retail sales for September / prev.: 1.2% / actual: 2.4% / forecast: 1.0% / GBP/USD — down
UK retail volumes in August rose 2.4% year-on-year, comfortably beating expectations and exceeding long-run averages of the past three decades. A strong consumer uptick followed a modest July rise, temporarily supporting the retail sector ahead of the autumn season. The September consensus foresees a sharp cooling in retail turnover. A marked pullback in consumer spending will weigh on the pound.
October 23, 10:30 / Germany / ***/S&P Global manufacturing PMI preliminary for October / prev.: 54.3 / actual: 53.9 / forecast: 53.5 / EUR/USD — down
Germany's manufacturing sector maintained solid expansion in September, with a composite PMI of 53.9, near two-year highs. Growth was supported by robust output and an expanding order book, driving capacity utilization to its highest since spring 2022 and sharply slowing job cuts at factories. Manufacturers' 12-month expectations hit a February high despite logistic disruptions and persistent energy price pressure. A lower print could weaken the euro.
October 23, 10:30 / Germany / ***/S&P Global services PMI preliminary for October / prev.: 49.7 / actual: 52.9 / forecast: 52.5 / EUR/USD — down
Germany's services PMI rose to a seven-month high in September, returning to clear expansion on the back of stronger new orders and rising investment spending. Firms increased hiring for the second month as backlogs built, though resurging input cost inflation pushed service providers to raise prices. The October preliminary reading expects a moderate slowdown in the pace of expansion. Some easing in services momentum would weigh on the euro.
October 23, 13:30, 15:00 / Russia / **/ Bank of Russia key rate decision and press conference / prev.: 14.0% / actual: 14.0% / forecast: 14.0% / USD/RUB — down
The Bank of Russia kept its key rate at 14% following the September meeting, pausing after ten consecutive easing steps. The pause was justified by a jump in core inflation in Q3, with seasonally smoothed annual growth hitting 11.6% due to refinery disruptions and a spike in fuel tariffs. While the central bank treats the price shock as largely exogenous and expects disinflation to resume, labor market tightness persists amid record low unemployment and consumer spending is slowing only moderately. The decision to remain tight and the regulator's readiness to counter inflationary risks will support the ruble.
October 23, 15:30 / Canada / **/Retail sales for August / prev.: 5.2% / actual: 5.1% / forecast: 4.9% / USD/CAD — up
Canada's retail sales rose 5.1% year-on-year in July, exceeding the long-run market benchmark of 4.65%. The consumer sector remained resilient near strong June levels, providing solid support for domestic demand. The August consensus expects retail growth to slow. Cooling consumer activity would weigh on the Canadian dollar.
October 23, 16:45 / USA / ***/S&P Global manufacturing PMI preliminary for October / prev.: 53.9 / actual: 55.9 / forecast: 55.5 / USDX (six-currency USD index) — down
US manufacturing business activity held at 55.9 in September, marking the best reading since spring 2022. The industrial impulse was supported by inflows of orders from the public sector and tech firms, allowing factories to raise output for the sixteenth consecutive month and to accelerate hiring at the fastest pace in five years. At the same time export demand remained under pressure from trade tariffs and expensive logistics, and lengthening supplier lead times coincided with renewed upward pressure on input costs. The preliminary October reading is expected to show a moderate slowdown in manufacturing growth. A weakening of industrial momentum would weigh on the US dollar.
October 23, 16:45 / USA / ***/ S&P Global services PMI preliminary for October / prev.: 56.5 / actual: 58.8 / forecast: 58.0 / USDX — down
The US services sector showed its strongest expansion since summer 2021 in September, extending a six-month growth run. High domestic demand produced the strongest inflow of new orders in more than four years, led by high tech industries, health care, and retail, which created capacity shortages and a continuous build-up of backlogs. To cope with the surge in clients, service firms increased payrolls for the third month running while facing sharp rises in gas and labor costs that forced them to raise prices. The October preliminary release anticipates some cooling of service expansion. Slower services growth would put downward pressure on the greenback.
October 23, 17:00 / USA / **/ University of Michigan consumer sentiment for October (leading) / prev.: 51.7 / actual: 48.1 / forecast: 46.3 / USDX — down
US consumer confidence fell in early October to its weakest levels since late spring as households expressed growing frustration with the rising cost of living. The assessment of current economic conditions plunged to a historic low of 44.7, reflecting adverse conditions for purchasing durable goods amid higher prices and costly credit. Lower income families with limited savings were hit hardest, their budgets exhausted by further spending pressure. Expected worsening of household sentiment raises the risk of further contraction in domestic demand and will weigh on the US dollar.
October 23, 17:00 / USA / **/ University of Michigan inflation expectations for October (leading) / prev.: 4.0% / actual: 4.6% / forecast: 4.7% / USDX — up
Short-term inflation expectations of US consumers continued to rise in October, reaching a five-month high. Consumers' belief that prices will keep rising over the year coincided with a lift in the five-year expectation to 3.5%, signaling a deeper entrenchment of pro-inflationary sentiment among the public. Analysts expect inflation expectations to edge higher in the next report. Persistently elevated household inflation fears strengthen the case for a hawkish Fed and support the US dollar.
October 22, 13:50 / UK — Andrew Bailey, Bank of England — GBP/USD
October 22, 15:15 / Eurozone — Fabio Panetta, ECB Governing Council member and Governor of the Bank of Italy — EUR/USD
October 22, 23:00 / UK — Catherine Braddick, Bank of England — GBP/USD
October 23, 10:55 / Eurozone — Patrick Montagner, ECB Supervisory Board — EUR/USD
October 23, 17:00 / Eurozone — Piero Cipollone, ECB Executive Board — EUR/USD
Additional senior central bank speakers are scheduled over these days; their comments typically drive FX volatility by signaling policy plans.
A link to economic calendar. All figures are year-on-year unless noted (m/m where applicable). Trade balance, export, and import values are in the country's currency. An asterisk denotes report importance for instruments available on the InstaForex platform. The indicated time is Moscow (GMT+3.00). Open a trading account here. See InstaForex market video news. For on-the-go access, download the MobileTrader app.
HIZLI BAĞLANTILAR
show error
Unable to load the requested language file: language/turkish/cookies_lang.php
date: 2026-10-22 07:24:22 IP: 172.18.0.1


 Bize Ulaşın